Latest from BCA Research
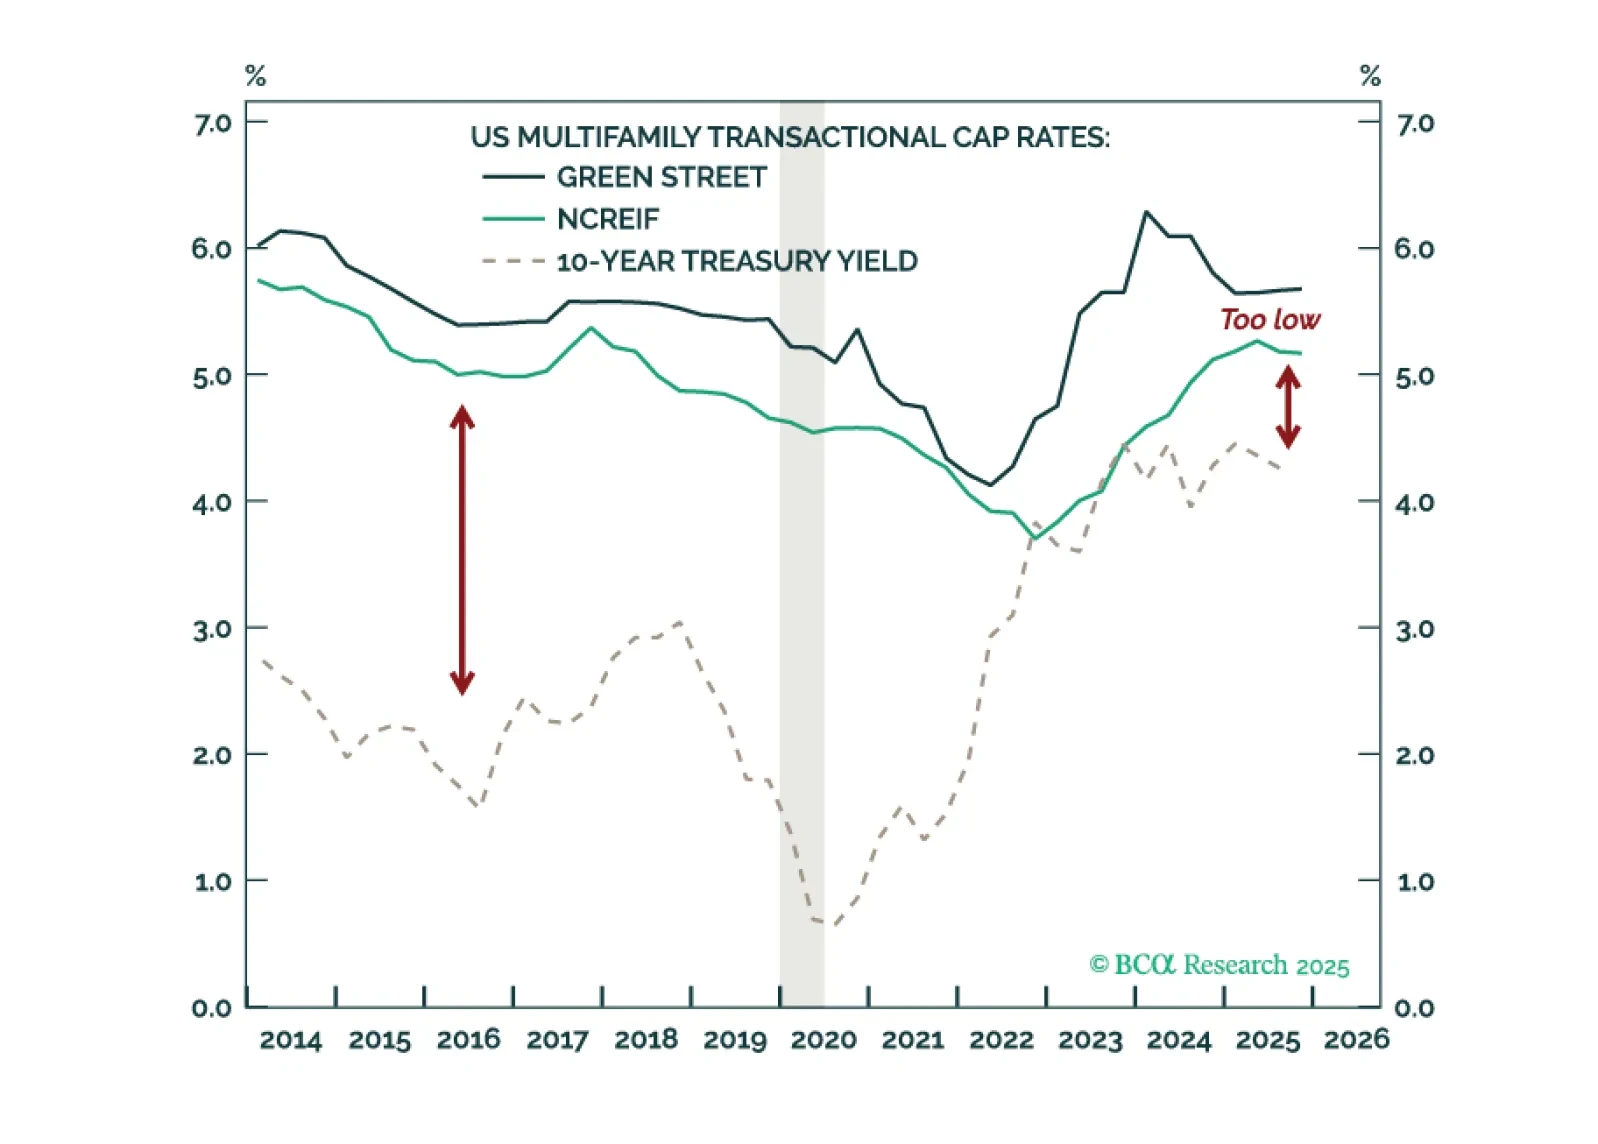
US Real Estate has been under pressure post-2022. This chartpack offers a snapshot of the cap rate cycle across measures, sectors, and cities. Industrial and Multifamily spreads remain tight while Office and Retail have peaked. Chicago and Houston differ as cities, but their Real Estate trends look increasingly alike.
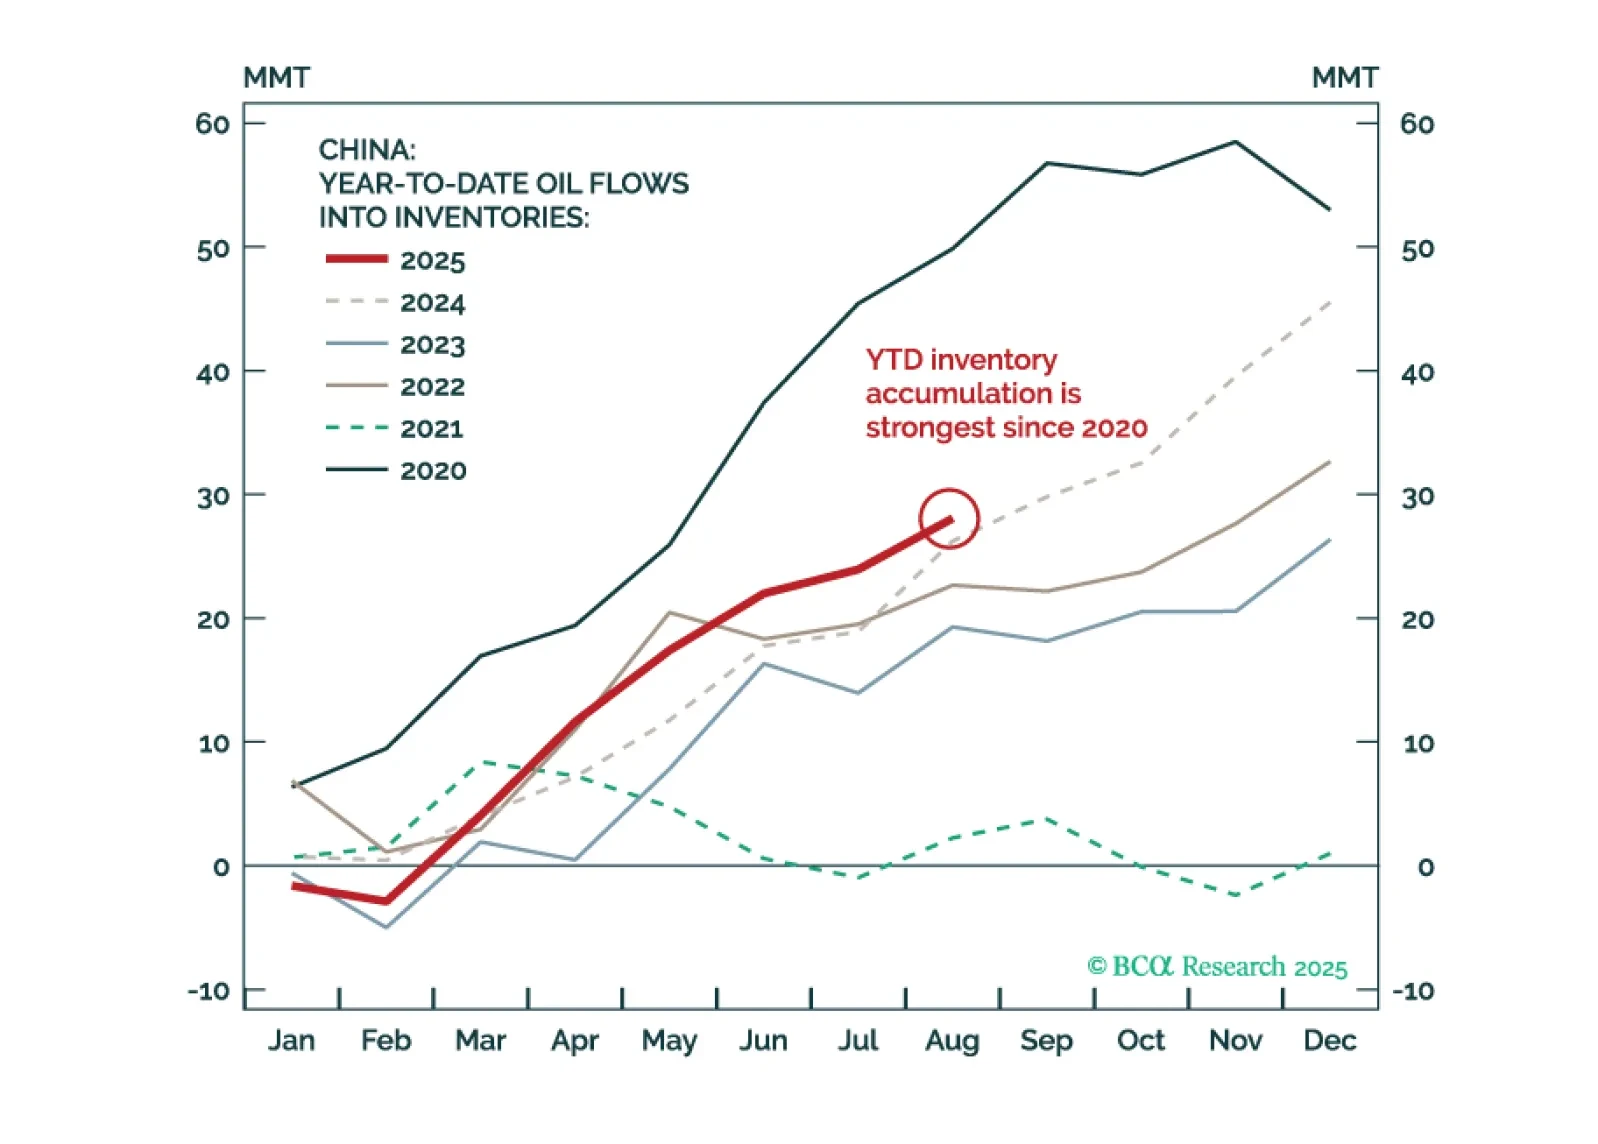
We remain cyclically short Brent but are tightening the stop loss to $73/bbl to guard against a geopolitics-driven upside break.

Monetary policy divergences are re-emerging. We rely on BCA’s Central Bank Monitor to assess the current policy stance of major central banks, and highlight the tactical opportunities across bond markets and currencies.
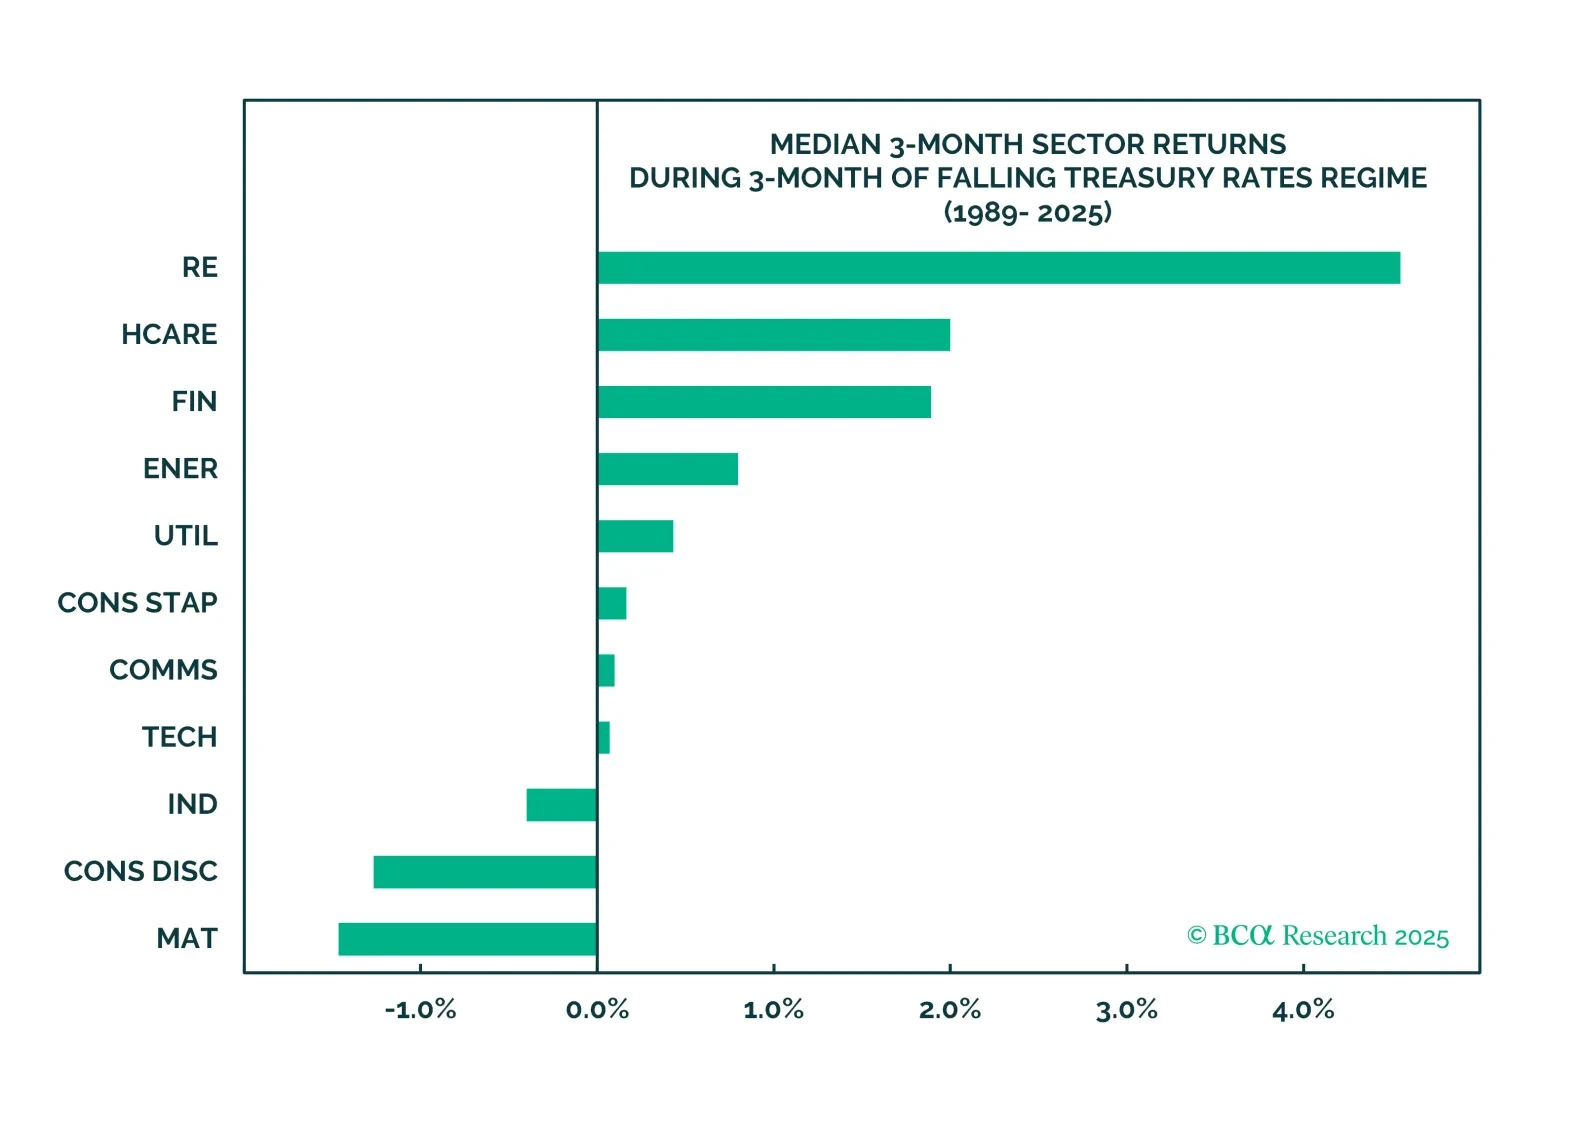
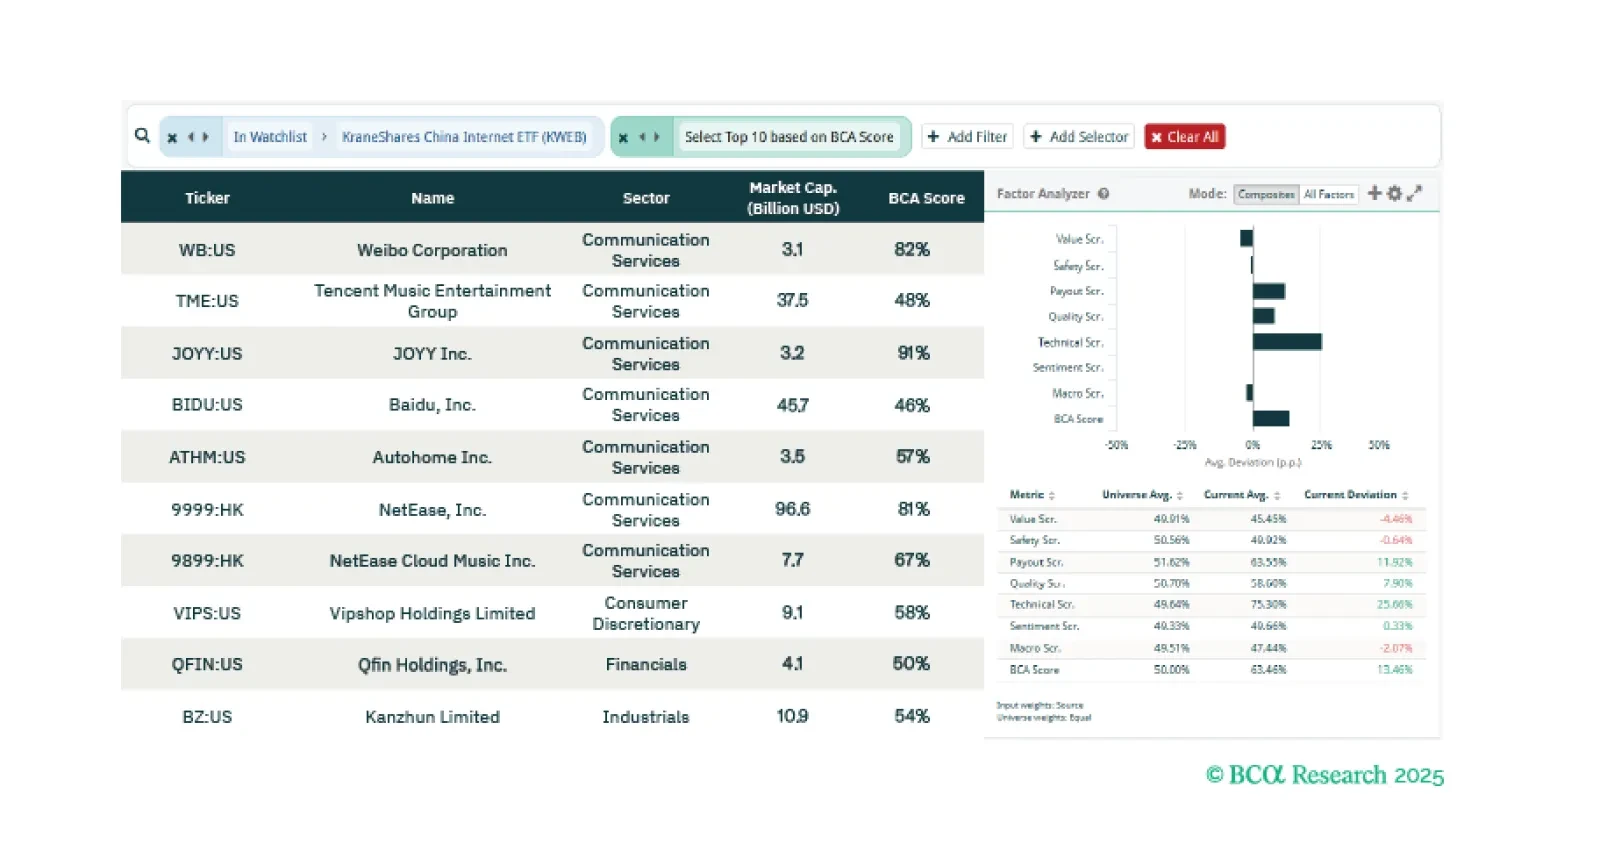
This week our screeners explore offshore Chinese internet stocks, US Healthcare equities, and sectoral opportunities in the Canadian bourse.

Rising Russia-NATO risks, tactical oil/gold trades, tougher sanctions on Russia (maybe China), China stimulus with ~5% growth target, and US checks on Trump’s ambitions will define Q4.
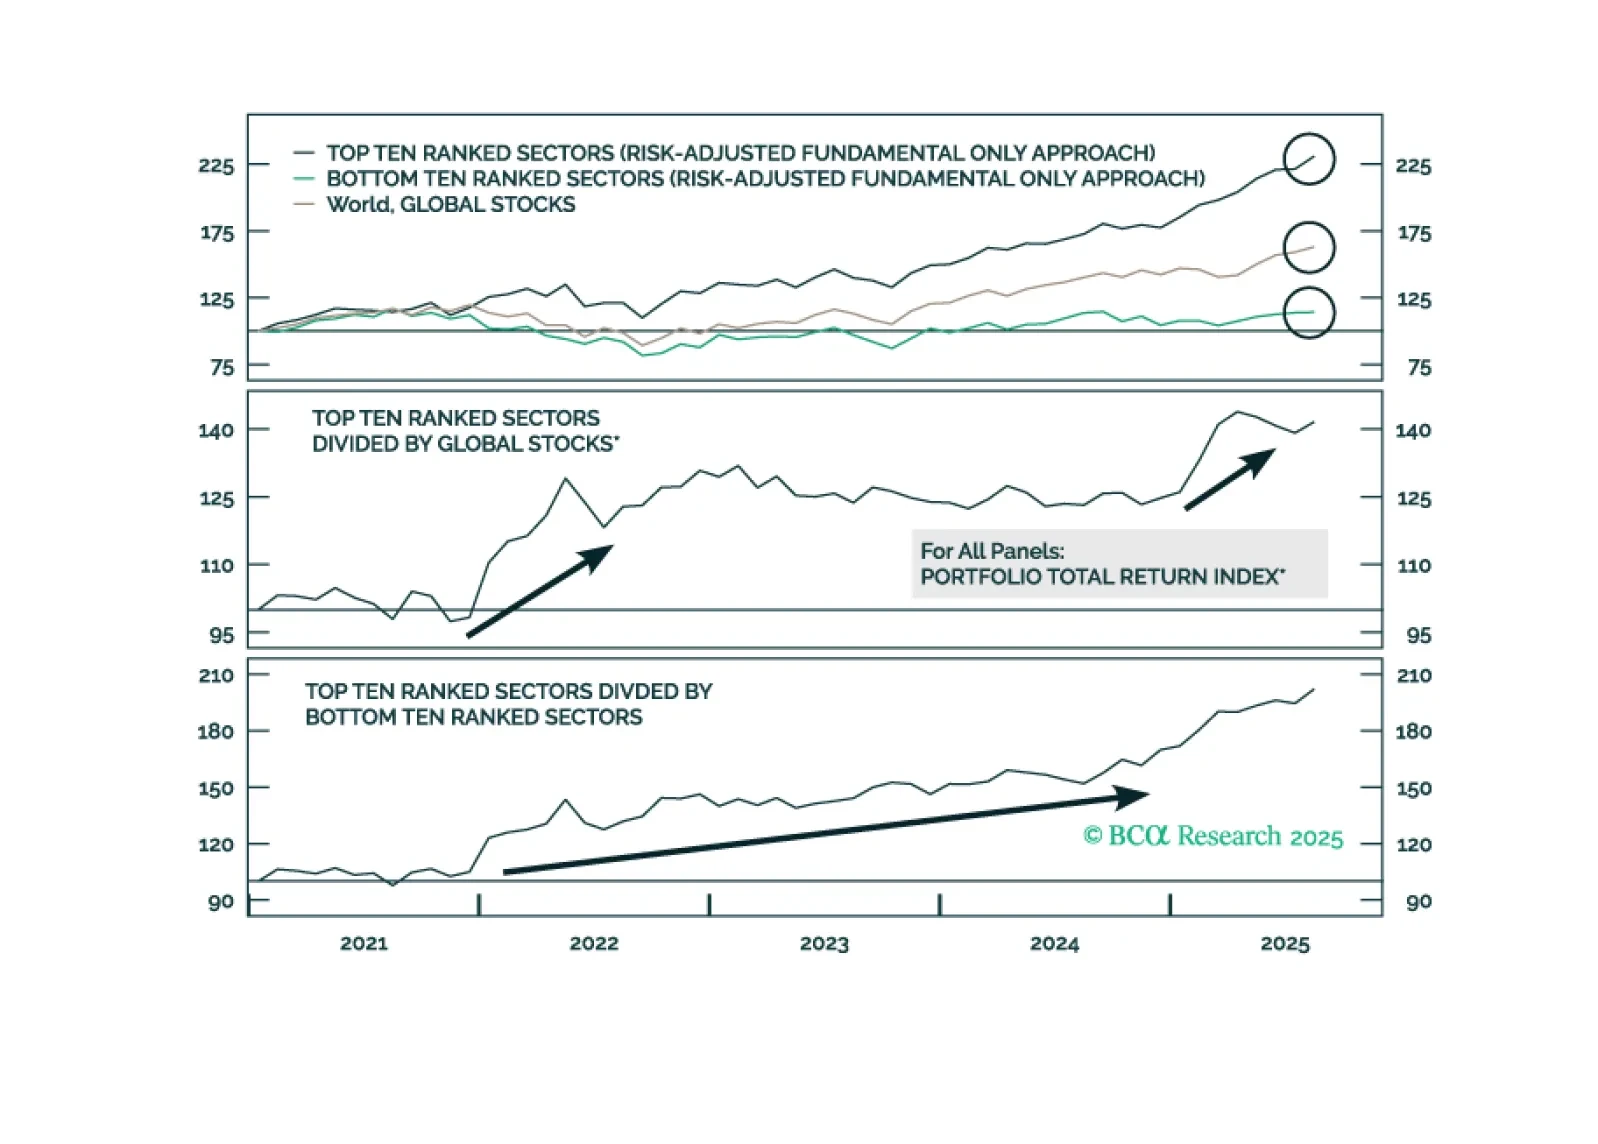
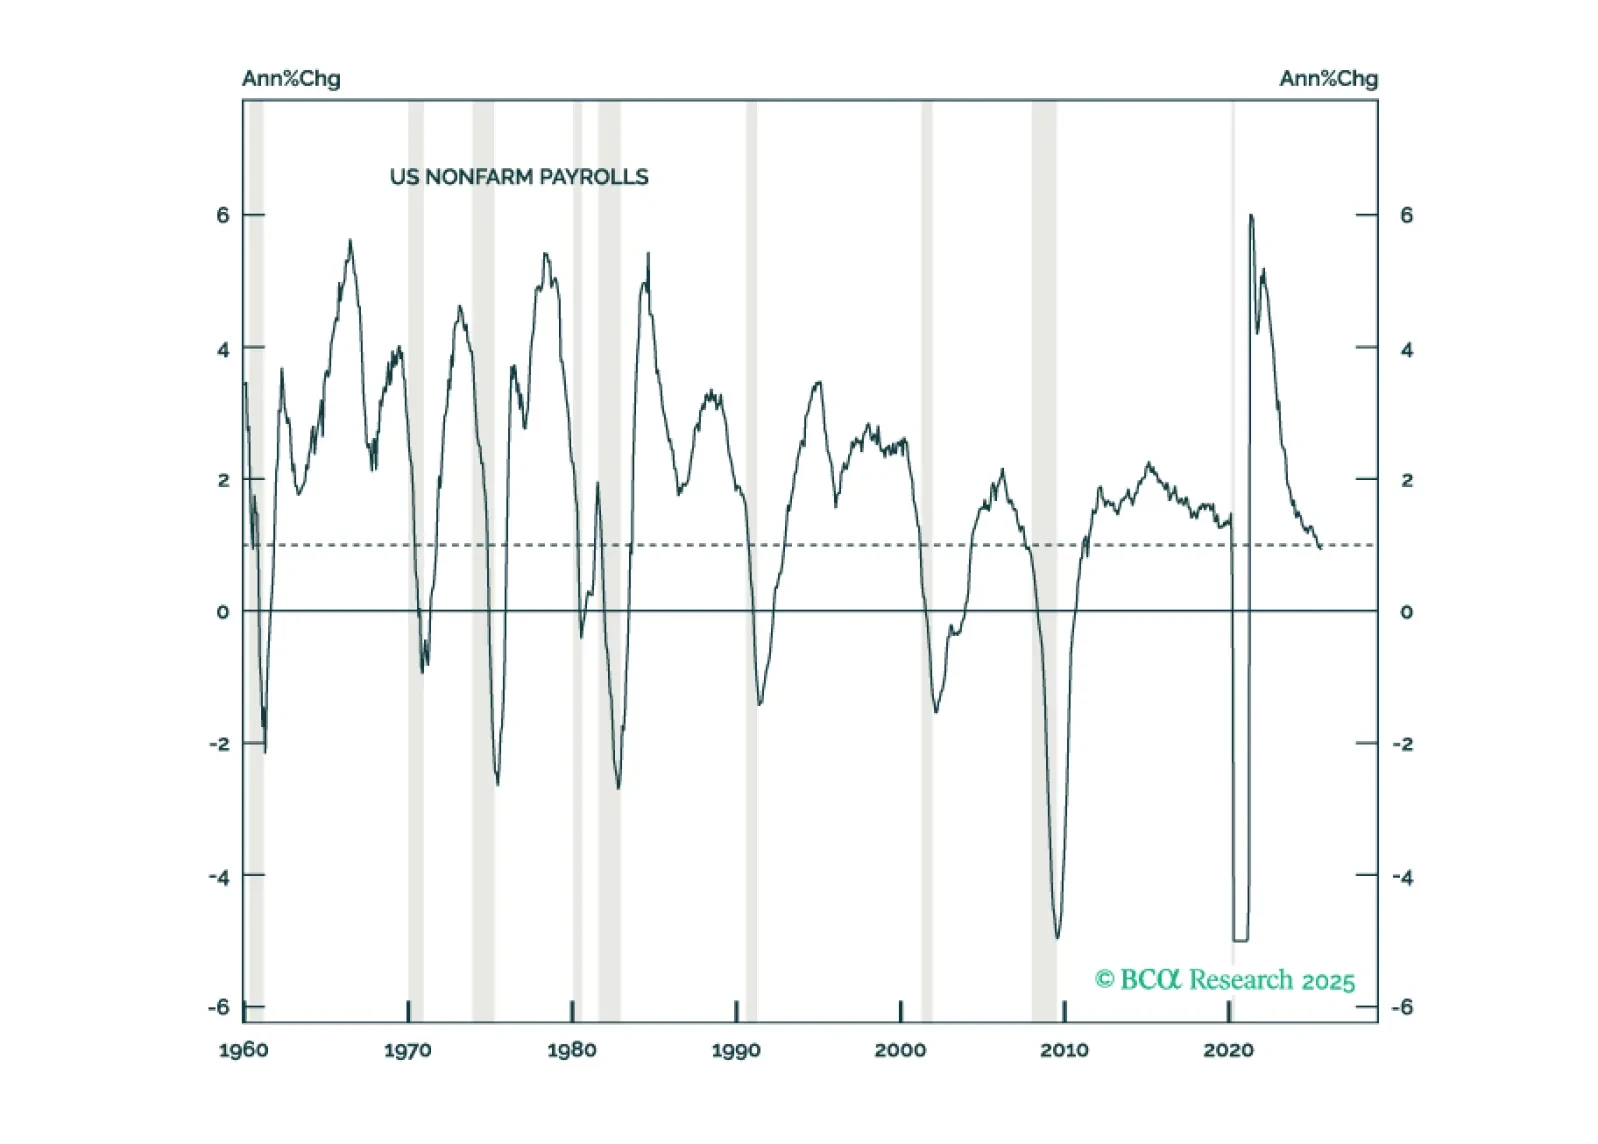
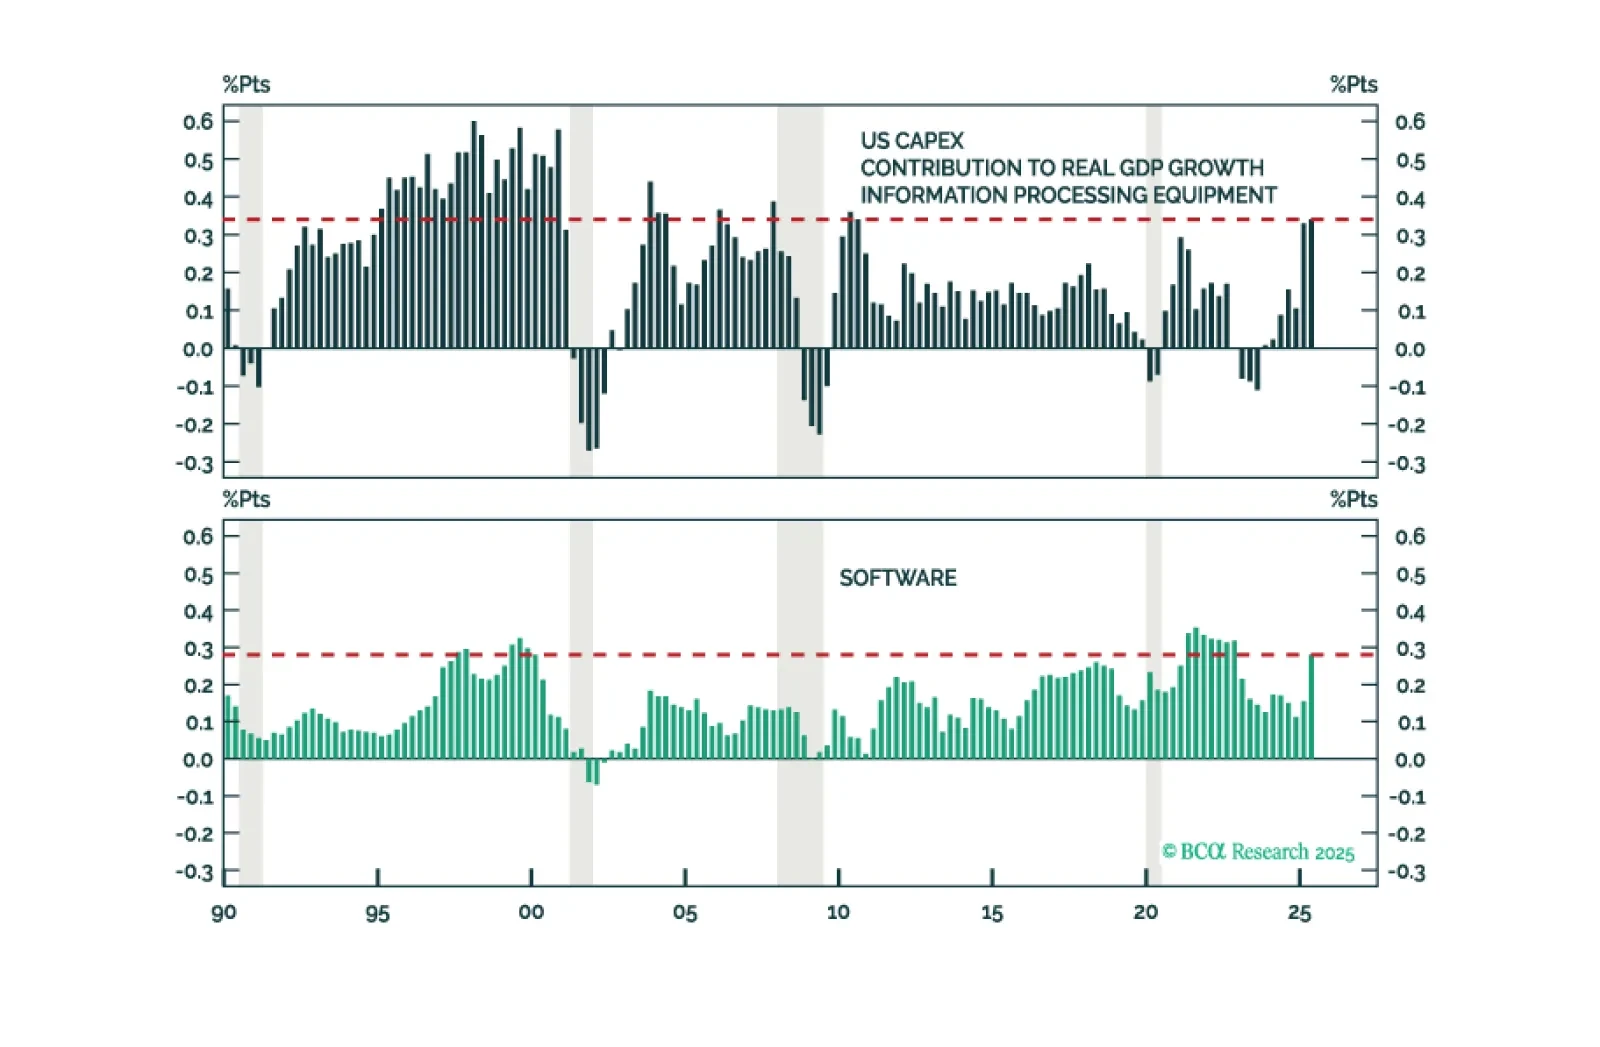
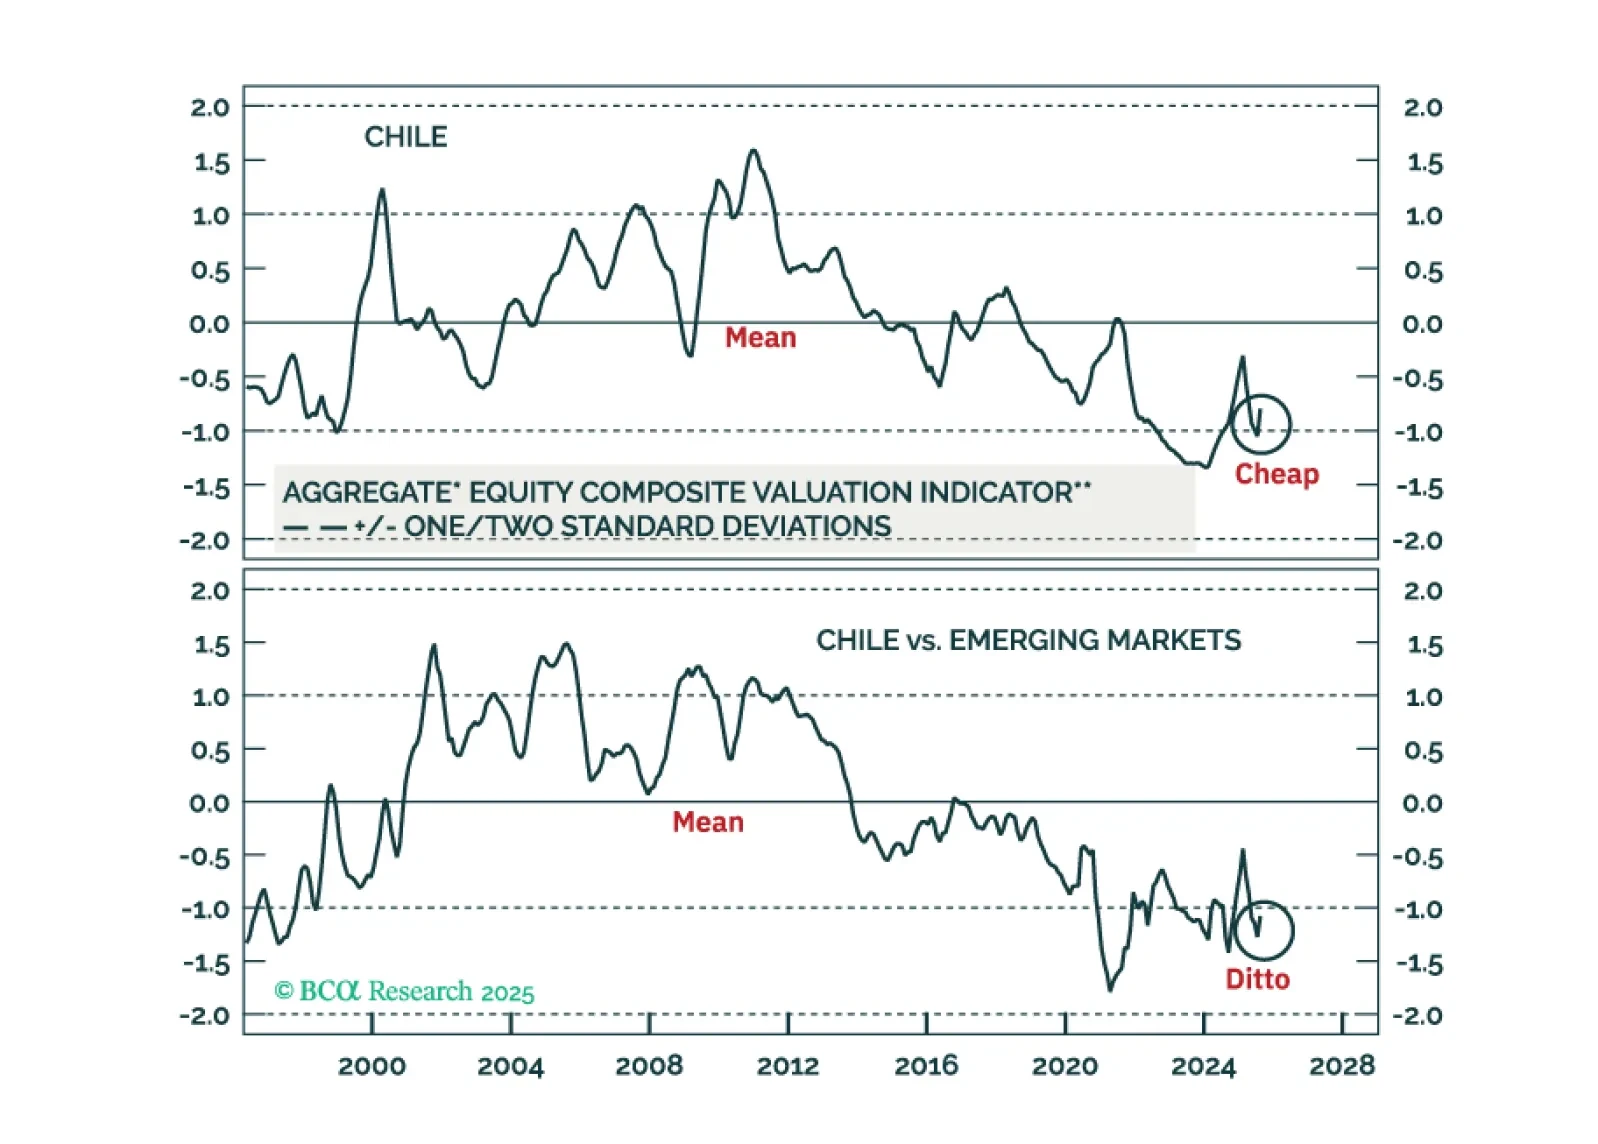
Chilean equities are undergoing a structural re-rating. A political swing back to a pro-business administration, a benign macro backdrop, and a resilient exchange rate will drive Chilean markets’ outperformance versus EM peers.